
Valuable items insurance
Insure the pieces that matter by name.
Homeowners and renters policies cap what they pay for jewelry, art and collectibles, often well below what those pieces are worth. Valuable items coverage lists each piece and its value, so a covered loss is measured against the amount on your schedule. We help you decide what to list and keep it current.
Takes about two minutes. No obligation. Licensed in NC and SC.
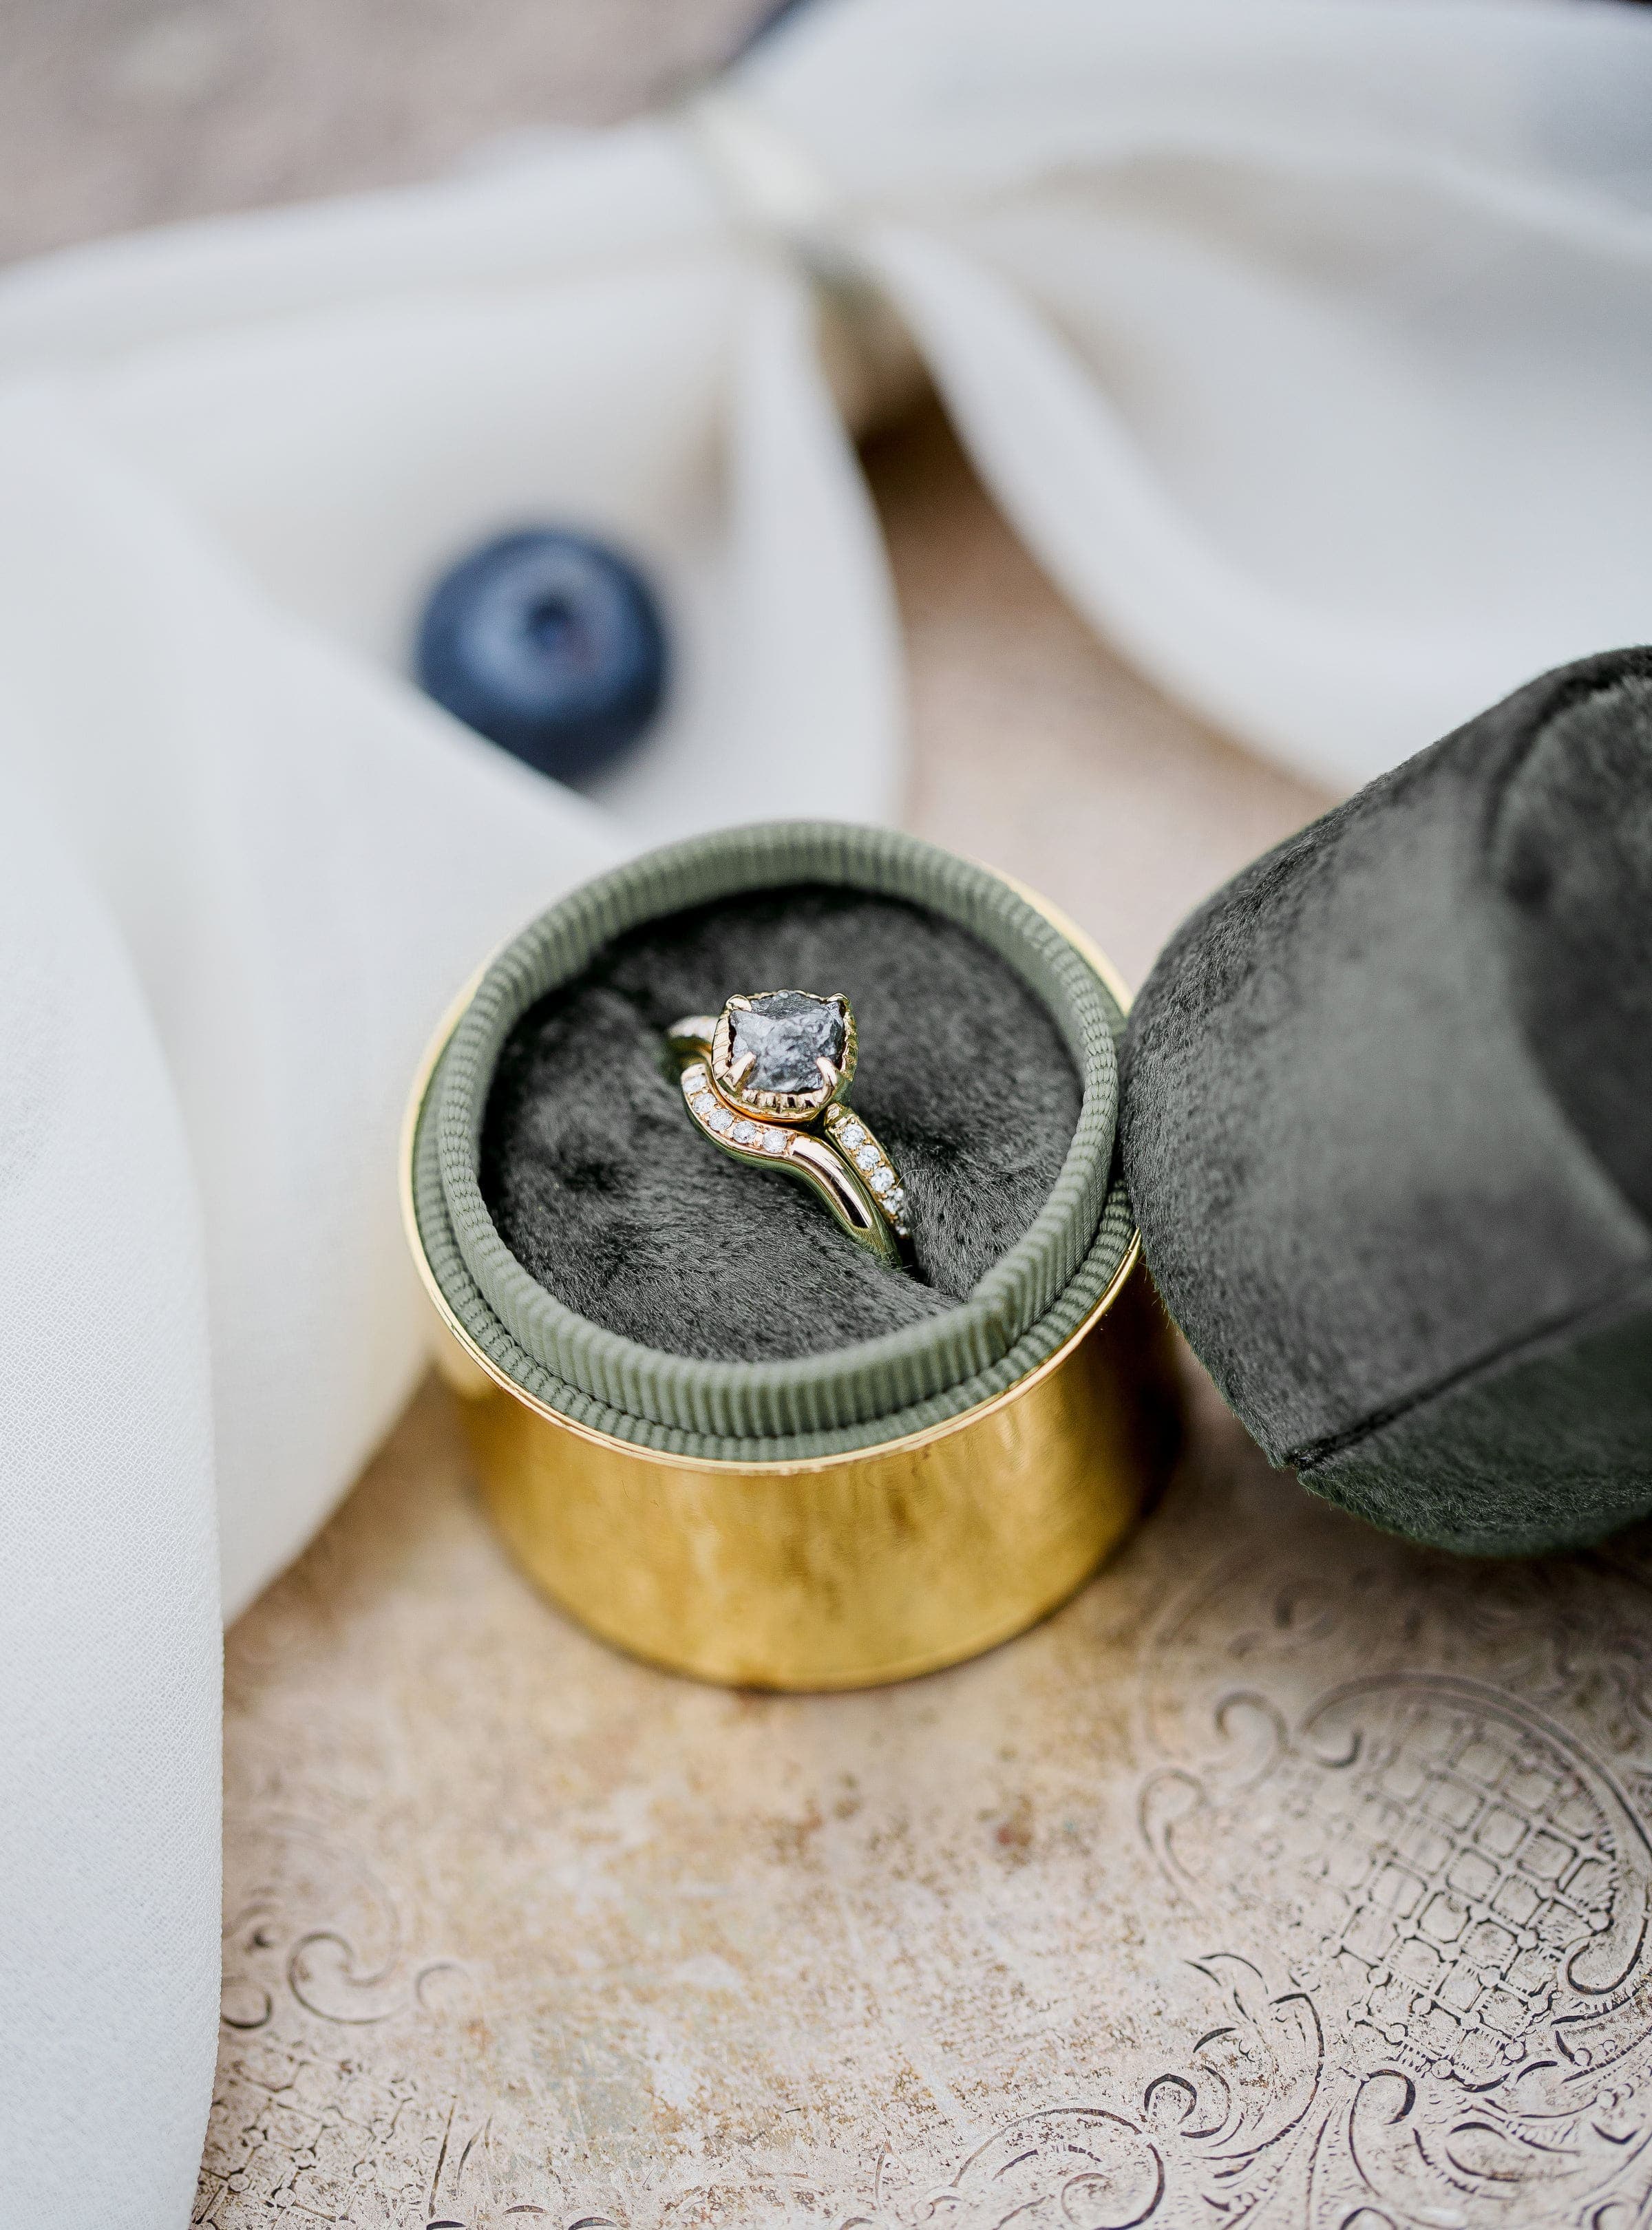
What a good valuable items policy answers.
The fine print on valuables is where many people get surprised. We read it with you before anything goes missing.
Is the piece covered for its full value?
Coverage scheduled at the appraised value, instead of your policy's lower limit for the category.
What if a stone falls out of its setting?
Loss and mysterious disappearance, which scheduled coverage often includes.
Are your items covered when you travel?
Coverage that follows your items away from home, and abroad on many policies.
Is there a deductible?
Scheduled items may carry a lower deductible, or none, depending on the carrier.
How is a loss settled?
Agreed value or replacement, and whether the carrier can replace the piece through its own jeweler.
What about breakage?
Accidental breakage of art, glass or china, which some policies leave out unless you add it.
Why families and collectors choose Pillar for their valuables.
Whether it's an engagement ring or a lifetime of collecting, we take the time to get the details right.
Scheduled or standalone
Some carriers add valuables to your homeowners policy; others write a separate policy. We compare both ways.
Know your limits
We show you the category limits in your current policy, and what each piece would be covered for once it's scheduled.
Help when something is lost
We help you gather appraisals, receipts and photos, and stay with the claim until it's resolved.
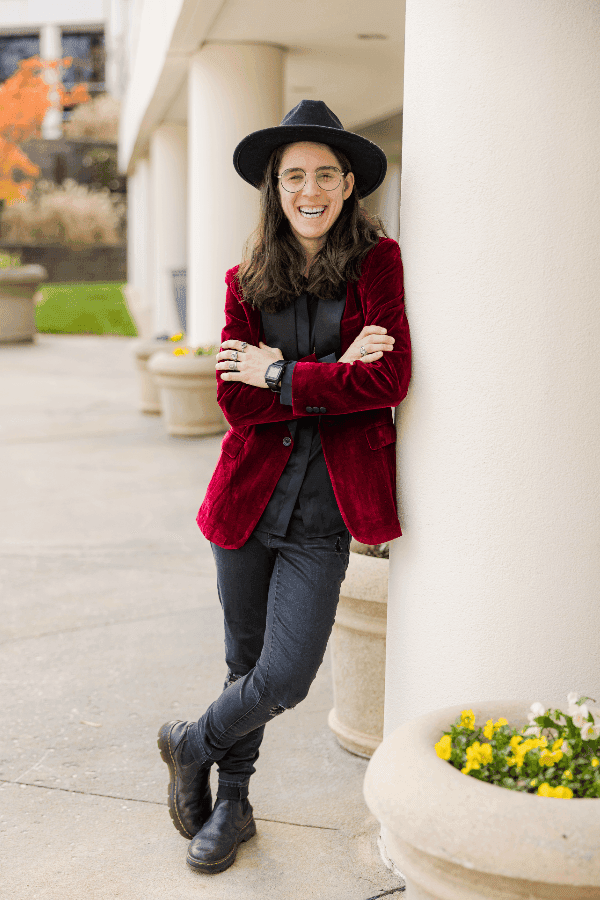
Your personal lines agent
Jessy Young
Personal Lines Agent, New Business. Jessy can help you sort out what to schedule and stays your contact when you add new pieces.
(919) 301-9786 ext. 100Often paired with valuable items.
Homeowners insurance
Your homeowners policy covers everyday belongings; scheduling covers the pieces above its limits.
Learn moreRenters insurance
Renters policies have category limits too, so a ring or a camera may need scheduling either way.
Learn moreHigh net worth coverage
Larger collections fit into one coordinated plan with your homes and liability.
Learn more
Already insured? Let us review it.
Send your current declarations page and we will tell you, plainly, whether better coverage is available at a lower cost.
Valuable items FAQs
See more FAQsDoesn't my homeowners policy already cover my jewelry?
It does, but usually only up to a set limit for certain kinds of property, especially when it's stolen. Jewelry, watches, furs, silverware and firearms commonly have these lower limits. If a piece is worth more than the limit, the difference is yours to cover. We'll look at your policy and tell you where its limits are.
Do I need an appraisal?
For most high-value pieces, yes. Carriers usually ask for a recent appraisal or a sales receipt to set the scheduled value, and some require one above a certain amount. Keep a copy somewhere other than your home, along with photos. Values change, especially for gold, diamonds and art, so plan to update appraisals every few years.
What kinds of items can be scheduled?
Most things of real value: engagement rings and other jewelry, watches, fine art, antiques, silverware, cameras, musical instruments, firearms, coins, stamps, and sports memorabilia or other collectibles. Some carriers write specialized policies for larger collections. If you're unsure whether something qualifies, ask us; it's easier to find out now than after a loss.
Is a scheduled item covered if I just lose it?
Often, yes. Scheduled coverage on many policies includes mysterious disappearance, such as a bracelet lost on a day at the lake or a diamond that slips from its prongs. A standard homeowners policy is generally built around theft and damage, not simple loss. Coverage varies by carrier, so we'll confirm how your policy handles it.