
Auto insurance
Auto coverage you understand before you need it.
North Carolina and South Carolina both require auto insurance, but two policies at the same price can pay very differently after a crash. We compare carriers for your cars and drivers, and explain in plain language what each policy covers and where it falls short.
Takes about two minutes. No obligation. Licensed in NC and SC.
What a good auto policy answers.
A low premium can hide thin coverage. Before you choose, we go through each of these questions with you.
Who pays if you hurt someone or damage their car?
Bodily injury and property damage liability, and whether your limits protect what you own.
Is your own car covered after a crash?
Collision coverage, and the deductible you pay before it starts.
What about a fallen tree, a hailstorm or a deer?
Comprehensive coverage for theft, weather, fire, flood and animal strikes.
What if the other driver has little or no insurance?
Uninsured and underinsured motorist coverage for your injuries and, depending on the policy, your car.
Will you have a car while yours is being repaired?
Rental reimbursement and towing, with their daily and per-claim limits.
What if you owe more than the car is worth?
Gap or loan and lease payoff coverage for a financed or leased car.
Why Carolina drivers choose Pillar.
We are an independent agency with offices in Raleigh and Charlotte, and we are a phone call away when something happens to your car.
We compare, you choose
We quote the same cars, drivers and limits with several of the carriers we work with, so you can see what each one charges and what it includes.
Limits you can read
What does 100/300/100 actually pay? We explain each number on your policy, and where a low limit could leave you exposed, before you sign.
On your side after a crash
Call us after an accident. We help you start the claim, explain what happens next and follow up with the carrier until it is resolved.
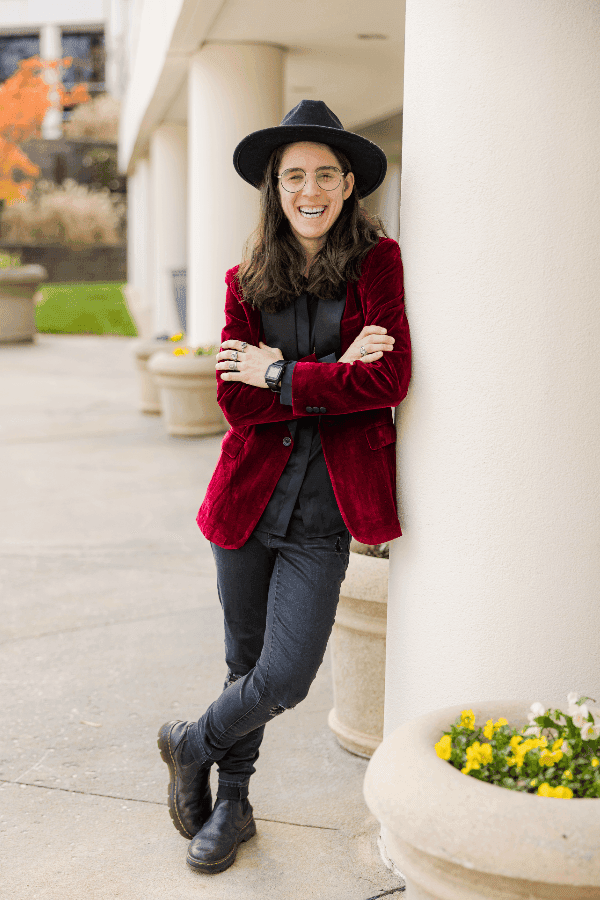
Your personal lines agent
Jessy Young
Personal Lines Agent, New Business. Jessy can walk you through the options for every car and driver in your household, and she stays your contact after your policy starts.
(919) 301-9786 ext. 100Often paired with auto.
Personal umbrella
Extra liability above your auto and home limits, for the serious accident that outruns your policy.
Learn moreUninsured and underinsured motorists
Protection for you and your passengers when the driver at fault carries too little insurance, or none.
Learn moreHomeowners insurance
Many carriers offer a discount when the same company insures your home and your cars.
Learn more
Already insured? Let us review it.
Send your current declarations page and we will tell you, plainly, whether better coverage is available at a lower cost.
Auto FAQs
See more FAQsHow much liability coverage should I carry?
The state minimum is a floor, not a recommendation. North Carolina's minimum liability limits are 50/100/50 for policies written or renewed on or after July 1, 2025; South Carolina's are 25/50/25. One serious crash can bring medical bills and lost wages well beyond those amounts, and what your policy doesn't pay can fall to you. A good rule is to carry limits that protect what you own and earn, and to add a personal umbrella if you have more at stake.
Do I need collision and comprehensive on an older car?
If the car is financed or leased, your lender typically requires both. If it is paid off, compare what the car is worth with a year of premium for the coverage plus your deductible. When those numbers get close, dropping collision can make sense. Comprehensive often costs less than collision and can still be worth keeping for theft, storms and deer. We will run the numbers with you.
How can I lower my auto insurance premium?
Keep a clean driving record, choose a higher deductible if you can comfortably pay it, and ask about discounts for insuring your home and cars together, for more than one vehicle, for good students and for safety features. Which discounts apply depends on the carrier, which is one reason comparing several helps. A review each year also catches drivers, cars and coverage that have changed.
Am I covered when I drive for a rideshare or delivery app?
Often not. Many personal auto policies exclude or limit coverage while you drive for pay, and the app company's coverage may not apply until you accept a ride or an order. Some carriers offer an endorsement that helps fill that gap. Tell us before you start driving for an app, so we can look for a way to close it.