
Rental property insurance
Protect your rental property and the income it earns.
A homeowners policy usually isn't written for a home you rent to someone else. Rental property insurance covers the building, the rent you could lose after a covered loss, and your liability as a landlord. We help you get it right for each property you own in the Carolinas.
Takes about two minutes. No obligation. Licensed in NC and SC.
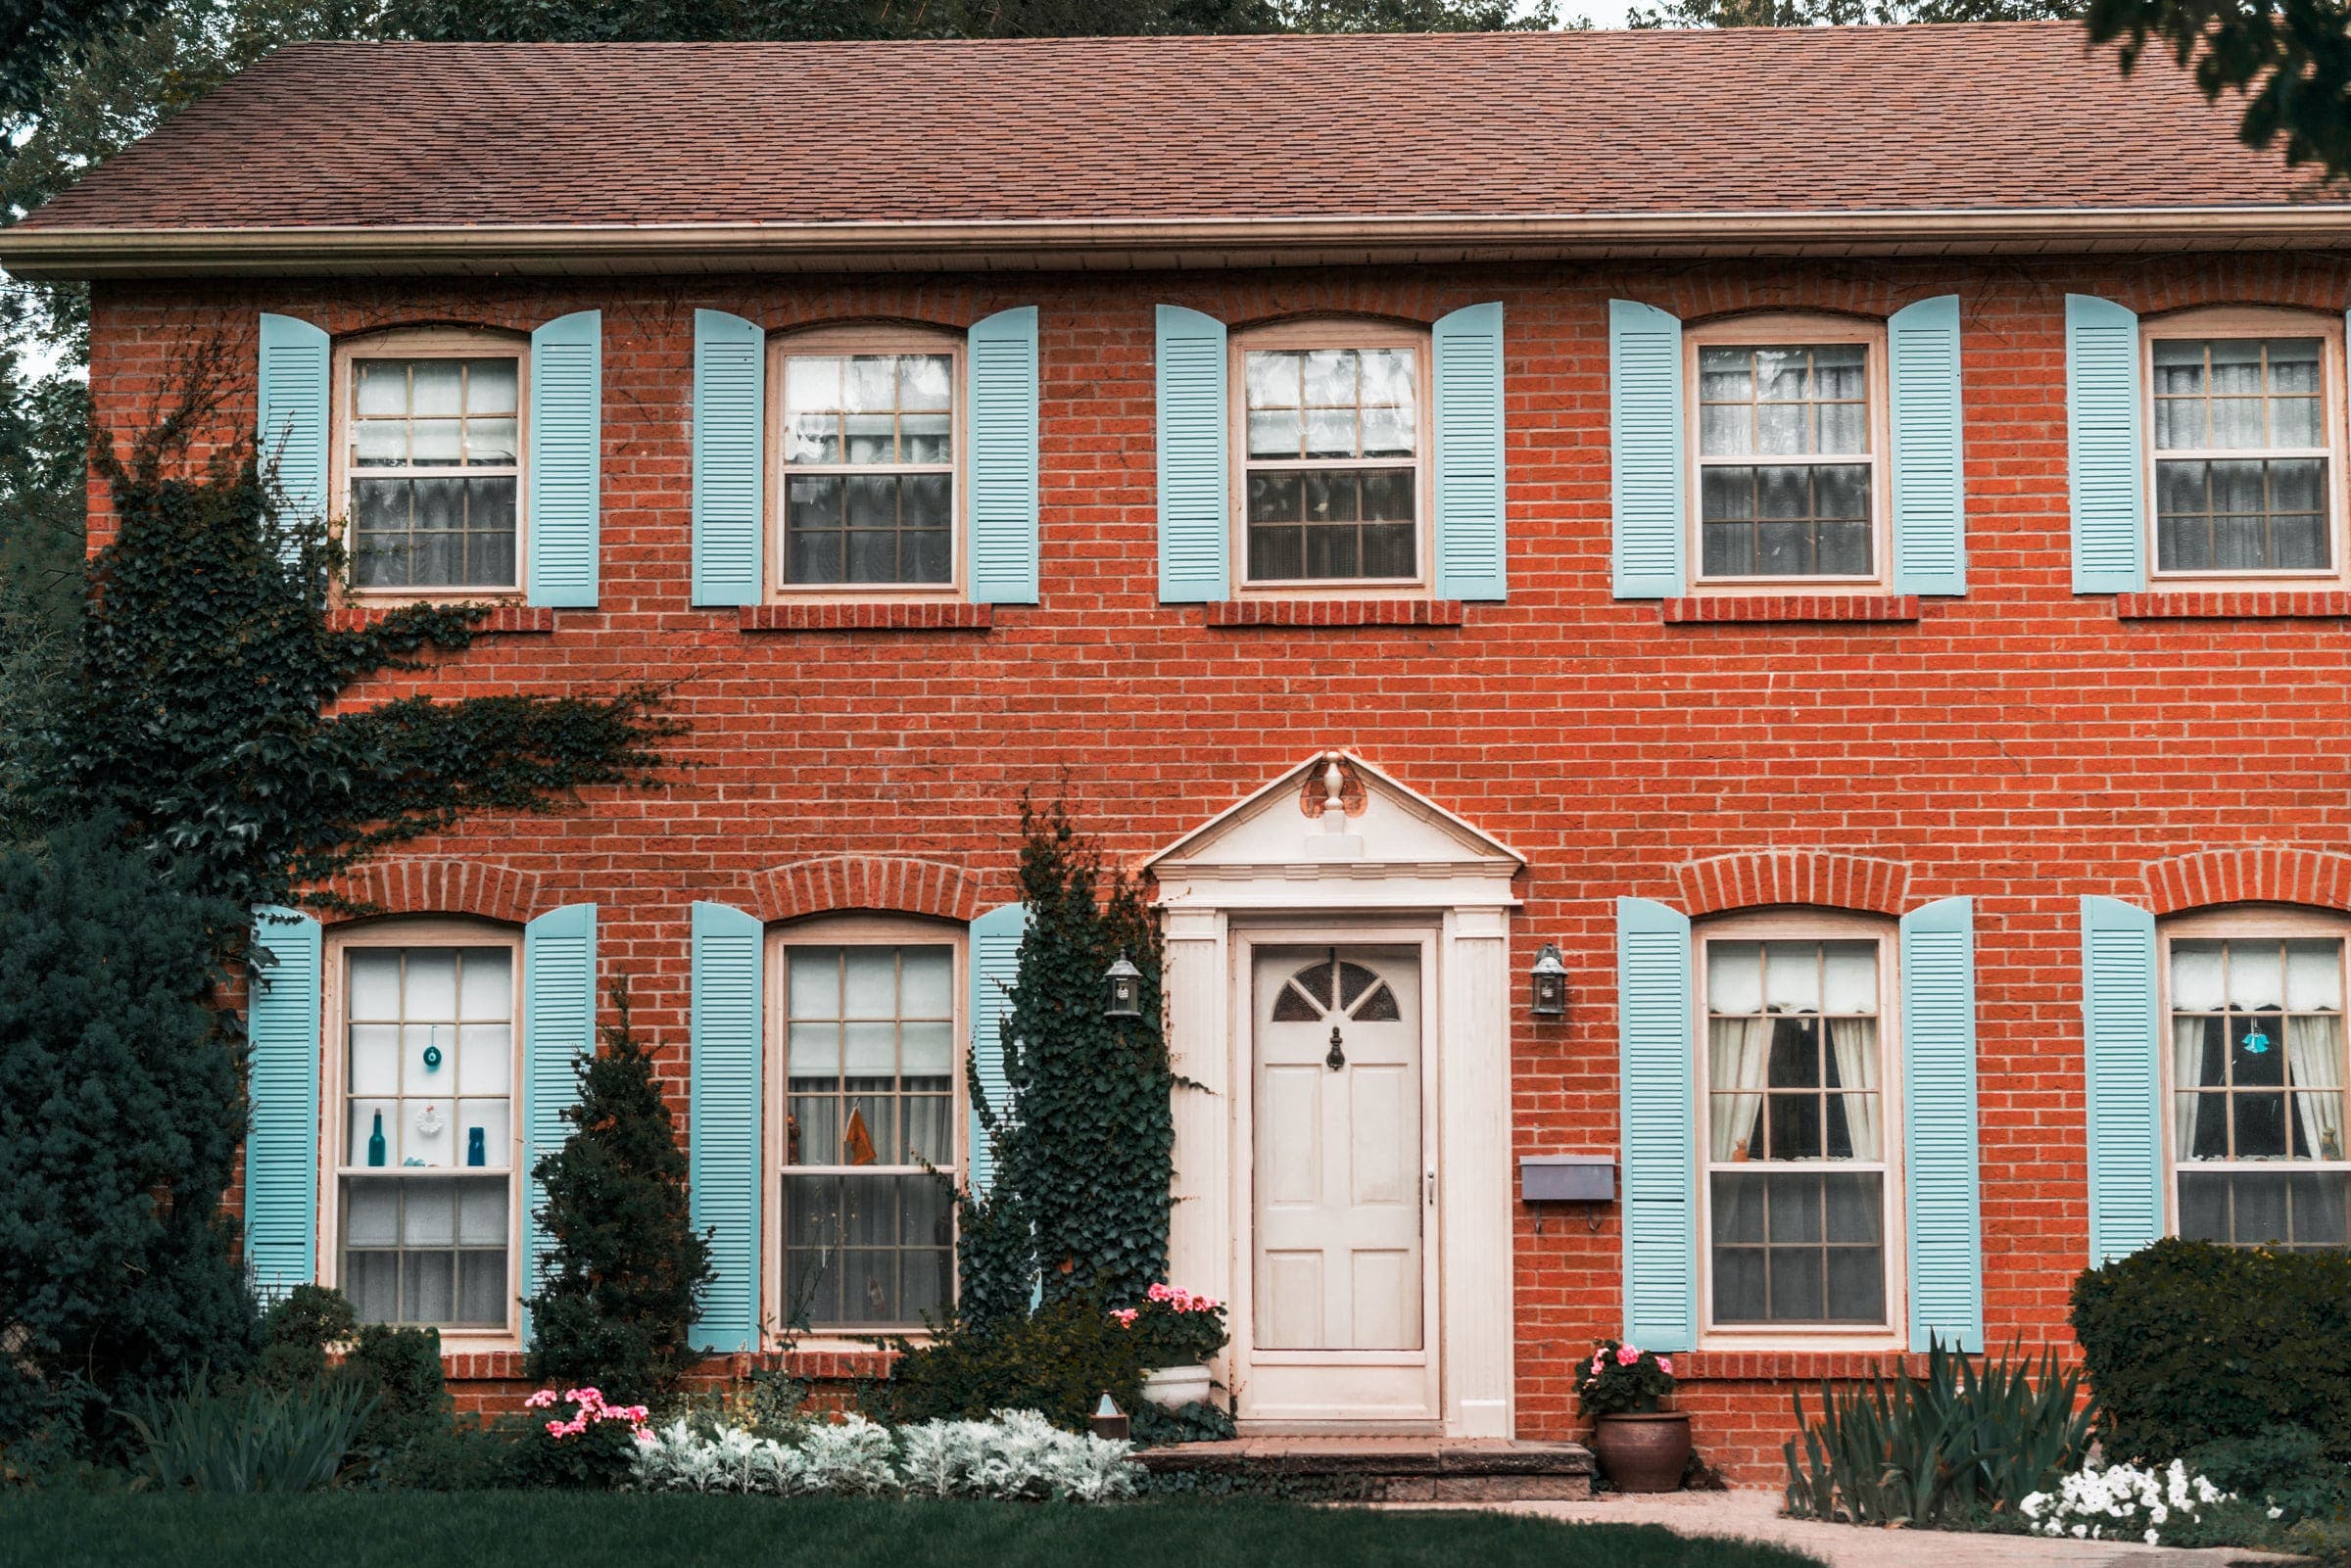
What a good rental property policy answers.
Landlord policies come in several forms, and the differences show up after a loss. We go through them with you.
Would the building be rebuilt or depreciated?
Dwelling coverage at replacement cost or actual cash value, and which one you have.
Will you lose rent if the home is unlivable?
Fair rental value, which replaces lost rent while covered damage is repaired.
What if a tenant or visitor is hurt?
Landlord liability for injuries on the property and the cost of defending a claim.
Are the appliances and furnishings you provide covered?
Property you own at the rental, like a refrigerator, window units or furniture in a furnished rental.
What if the home sits empty between tenants?
Vacancy limits, which can restrict coverage once a home has been empty for a while.
Is a short-term rental covered?
Whether nightly or weekly rentals need a different policy or an endorsement.
Why landlords choose Pillar.
Whether you rent out one house or several, you get a local agent who knows each of your properties.
We compare, you choose
We compare landlord policies from the carriers we work with, property by property, and look for ways to keep them organized as you add more.
Plain-language policies
We explain how vacancy, renovations and short-term rentals affect your coverage before they become a problem at claim time.
An advocate at claim time
When a tenant reports damage or a storm hits, we help you file and follow through with the carrier.
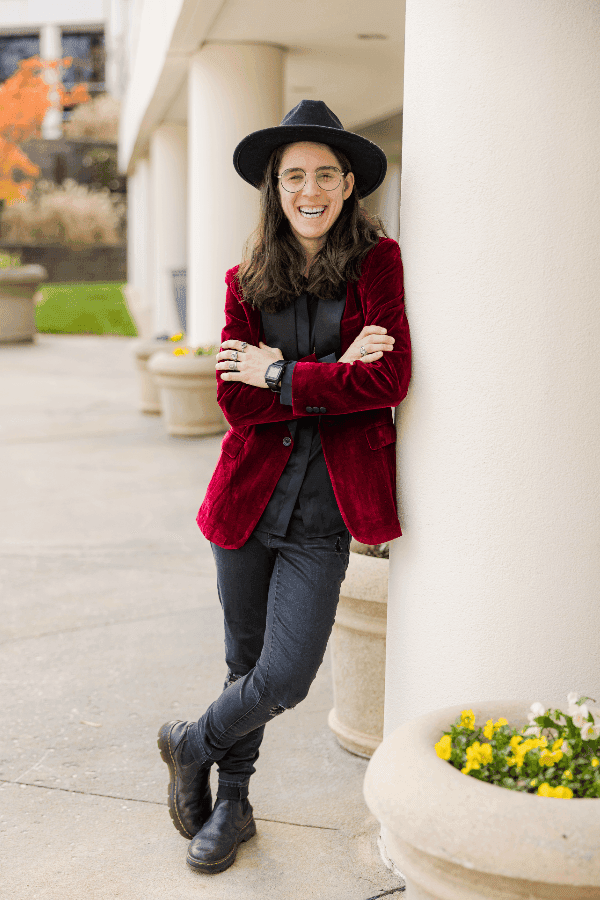
Your personal lines agent
Jessy Young
Personal Lines Agent, New Business. Jessy can review your rental properties with you and stays your contact as you add more.
(919) 301-9786 ext. 100Often paired with rental property.
Personal umbrella
Owning rentals adds liability exposure, and an umbrella sits above each property's limits.
Learn moreFlood insurance
Landlord policies typically exclude flood, and a flooded rental earns no rent while it's repaired.
Learn moreRenters insurance
Asking tenants to carry renters insurance covers their belongings, which your policy doesn't.
Learn more
Already insured? Let us review it.
Send your current declarations page and we will tell you, plainly, whether better coverage is available at a lower cost.
Rental property FAQs
See more FAQsCan I use my homeowners policy if I rent out my home?
Usually not for long. Homeowners policies are written for homes you live in, and many limit or exclude coverage once the home is rented to others. If you've moved and kept your old house as a rental, or you rent your home out for part of the year, tell us before there's a claim. We'll check your policy and move you to the right coverage if needed.
What about short-term rentals?
Renting by the night or the week, whether it's a beach house on the coast or a room in your home, is treated differently from a long-term lease. Some carriers offer an endorsement for occasional short-term rentals; others require a separate policy, especially when renting is a business for you. We'll find coverage that matches how you actually rent.
Does landlord insurance cover my tenant's belongings?
No. Your policy covers the building and the property you own there, such as appliances you provide. Your tenant's furniture, clothing and electronics aren't covered by it. Many landlords require renters insurance in the lease, which protects the tenant's belongings and gives them liability coverage of their own.