
Mobile and manufactured home insurance
Coverage made for manufactured and mobile homes.
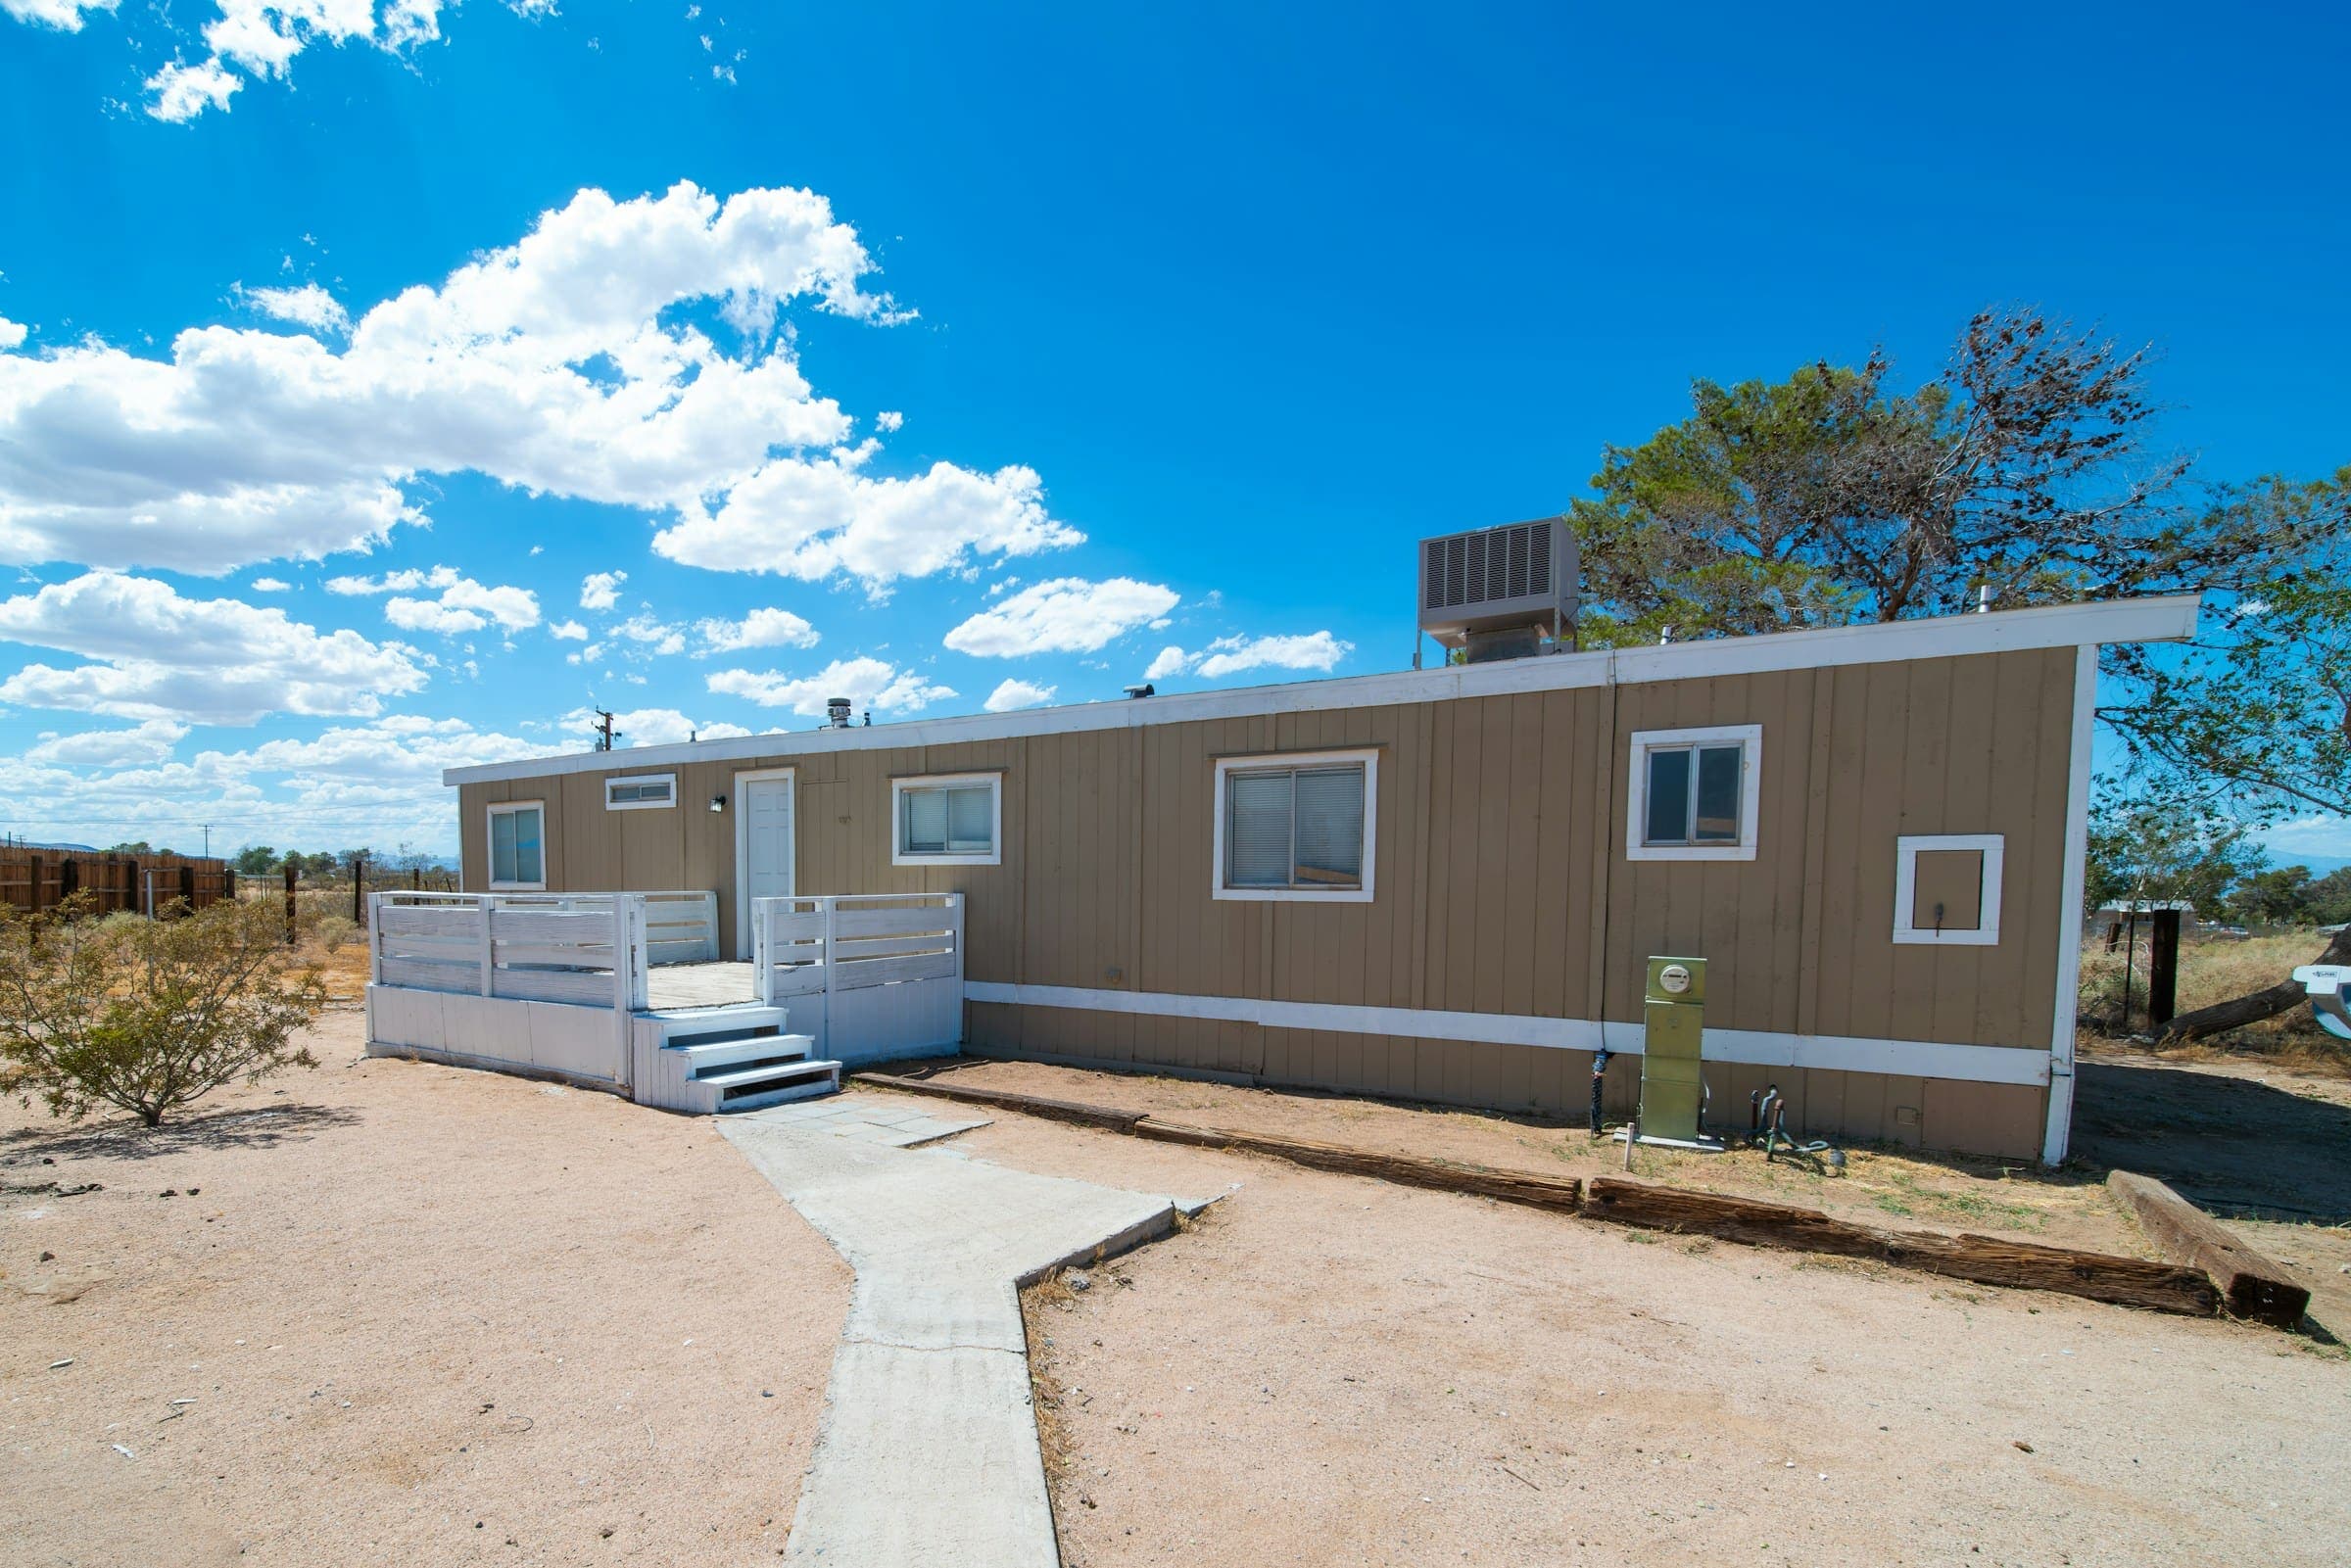
Manufactured homes need policies written for how they're built and where they sit. We compare options for the home, the structures you've added and everything inside, and explain the differences in plain language.
Takes about two minutes. No obligation. Licensed in NC and SC.
What a good mobile home policy answers.
Manufactured home policies vary more than most people expect. These are the questions we make sure yours answers.
Would the home be replaced or depreciated?
Replacement cost versus actual cash value, which matters more as the home ages.
Are your porch, deck and shed covered?
Other structures, including carports, steps and additions you've built.
What about storm damage?
Wind and hail coverage, and any separate deductible that applies to it.
Are your belongings covered?
Personal property, from furniture to electronics, and how it's valued after a loss.
What if someone is hurt at your home?
Personal liability and medical payments to others.
What if you move the home?
Coverage while the home is being transported, which some carriers offer as an option.
Why manufactured homeowners choose Pillar.
Not every carrier writes manufactured homes, and the ones that do don't all treat them the same.
We compare, you choose
We quote the carriers we work with that write manufactured homes, and look for discounts you may qualify for, including insuring your home and car together.
Plain-language policies
We explain how your home's age, setup and tie-downs can affect coverage, and what each policy pays after a loss.
An advocate at claim time
After a storm or a fire, we help you file, document the damage and follow through with the carrier.
Your personal lines agent
Jessy Young
Personal Lines Agent, New Business. Jessy can compare your manufactured home options with you and stays your contact after the policy starts.
(919) 301-9786 ext. 100Often paired with mobile and manufactured home.
Flood insurance
Mobile home policies typically exclude flood, and heavy rain can reach homes far from the coast.
Learn moreAuto insurance
Insuring your home and car together may earn a multi-policy discount with some carriers.
Learn morePersonal umbrella
Extra liability above your home and auto limits, if a serious injury claim exceeds them.
Learn more
Already insured? Let us review it.
Send your current declarations page and we will tell you, plainly, whether better coverage is available at a lower cost.
Mobile and manufactured home FAQs
See more FAQsIs mobile home insurance different from homeowners insurance?
It covers the same basics: the structure, other structures, your belongings, liability and loss of use. The differences are in how carriers rate and value manufactured homes. The home's age, how it's anchored, whether it sits on land you own or in a community, and how it's built all affect what's available and how a loss is paid. That's why comparing carriers matters.
Does the age of my home matter?
Often, yes. Some carriers limit coverage on older manufactured homes or offer only actual cash value, which pays the depreciated value after a loss. Others may offer replacement cost on newer homes. If your home is older, comparing several carriers improves your chances of finding coverage that fits. We can tell you what's available for your home's year and condition.
Do I need insurance if my home is paid off?
Lenders typically require coverage while there's a loan, but once it's paid off, the choice is yours. It's still worth keeping. A fire or a hurricane could cost you the home and everything in it, and liability coverage protects you if someone is hurt on your property. Without insurance, all of that comes out of your pocket.